
How to do a good job of non-standard equipment design?2020-11-30


News Center
News Center
-
-
 Analysis of the Global TFT LCD and Large-Size LCD Panel Industries from 2020 to 20252020-10-23
-
 TCL Overtook LG to Become the World's Second Largest TV Company As South Korean TV2020-10-15
-
 Artificial Intelligence, 5G Support "New Display" Ushered In the Moment of Highlight2020-09-30
-
 Global LCD Panel Prices Rise, China's Panel Companies Welcome the Moment of Highlight2020-09-30
-
 The Design and Application of Light Guide Plate in LCD TV2020-09-30
-
 Novo · Equipment | Intelligent REF Machine2020-09-23
-
 In 2020, The Analysis of The Development Status of The Global TV Panel Market2020-09-10
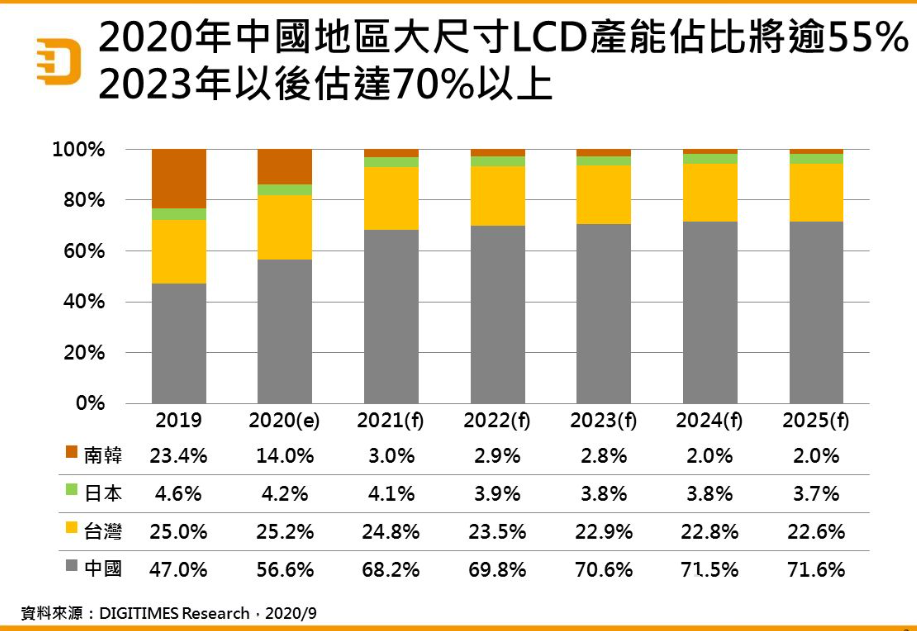
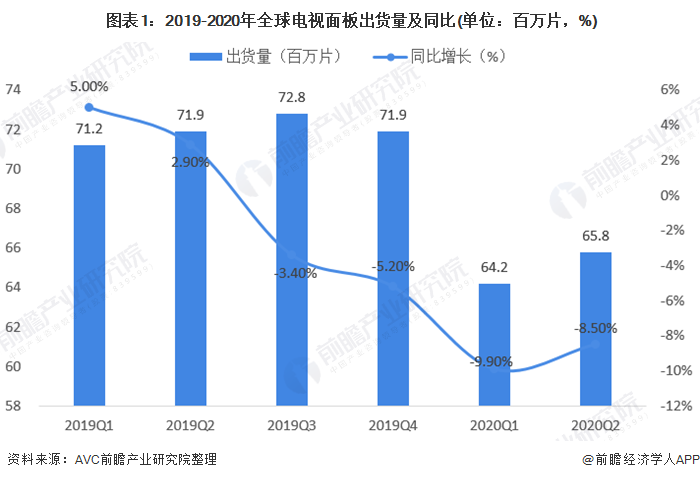
At the beginning of 2020, the global consumer market will face great challenges due to coVID-19 and changes in the global political and economic environment. On the one hand, the epidemic has a negative impact on the industrial chain's resumption rate, logistics and production; on the other hand, the decline in consumer confidence and the postponement of sports events have an impact on the overall TV shipment forecast. In the first half of 2020, 130 million TV panels were shipped globally, down 9.2% year-on-year, and the shipping area was 788m square meters, down 0.5% year-on-year. In recent years, the global production capacity pattern of TV panels has changed. Korean factories have shut down the production capacity of large-size LCD panels, and the market share of production capacity has been continuously reduced. However, Chinese panel manufacturers continue to release new production capacity, which has taken up nearly 50% of the market share in 2019.From the perspective of vendor shipments, BOE shipped the first place, with 22.8 million pieces shipped in the first half of 2020, with a shipping area of 14.4 million square meters. CSOT ranks second, with 1 million tablets shipped in the first half of 2020, covering an area of 137 million square meters. Panel prices fluctuate sharply in the first half of 2020, and prices are expected to rise in the second half. In addition, the 8K industry chain is becoming mature and is expected to usher in high-speed growth in 2021. In 2022, the global 8K scale is expected to exceed 7 million units and the penetration rate is expected to increase to 2.7%.
-
 The Latest Ranking | Global LCD TV Panel Market Monthly Shipments2020-09-09
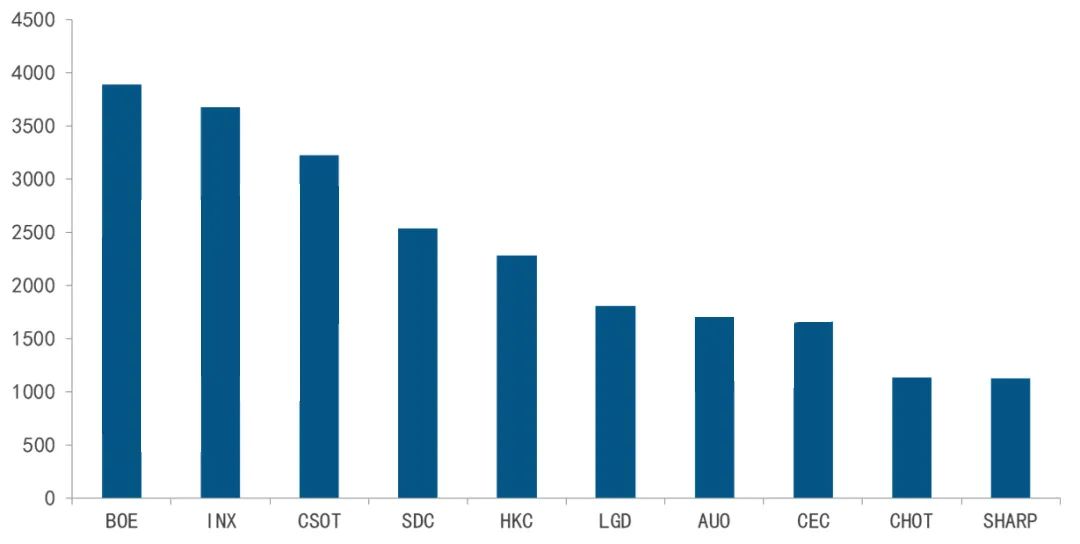
According to the newly released global TV LCD Panel Monthly Market Tracking report, in July 2020, global TV LCD panel shipments were 23.0m, down 4% year on year and down 2% month on month.
-
 TELEVISION Market Is Recovering & LCD Prices Are Soaring2020-08-27
Prices for large liquid crystal display (LCD) panels have hit record highs this year, driven by a recovery in the global TELEVISION market.