


In 2020, The Analysis of The Development Status of The Global TV Panel Market
2020.09.10
At the beginning of 2020, the global consumer market will face great challenges due to coVID-19 and changes in the global political and economic environment. On the one hand, the epidemic has a negative impact on the industrial chain's resumption rate, logistics and production; on the other hand, the decline in consumer confidence and the postponement of sports events have an impact on the overall TV shipment forecast. In the first half of 2020, 130 million TV panels were shipped globally, down 9.2% year-on-year, and the shipping area was 788m square meters, down 0.5% year-on-year. In recent years, the global production capacity pattern of TV panels has changed. Korean factories have shut down the production capacity of large-size LCD panels, and the market share of production capacity has been continuously reduced. However, Chinese panel manufacturers continue to release new production capacity, which has taken up nearly 50% of the market share in 2019.From the perspective of vendor shipments, BOE shipped the first place, with 22.8 million pieces shipped in the first half of 2020, with a shipping area of 14.4 million square meters. CSOT ranks second, with 1 million tablets shipped in the first half of 2020, covering an area of 137 million square meters. Panel prices fluctuate sharply in the first half of 2020, and prices are expected to rise in the second half. In addition, the 8K industry chain is becoming mature and is expected to usher in high-speed growth in 2021. In 2022, the global 8K scale is expected to exceed 7 million units and the penetration rate is expected to increase to 2.7%.
Supply was blocked in the first quarter and demand fell in the second.
The coVID-19 outbreak at the end of January in 2020 caused insufficient resumption of panel factories in mainland China after the Spring Festival, shortage of upstream raw materials, and obstructed logistics and transportation. In the first quarter, the shipment of TV panels dropped by 9.9% and 2.1% year-on-year. Control panel industry, concentrated in east Asia, basic recovery capacity at the end of March 2020, but the spread of the epidemic in the global lead to reduced demand TV, TV brand purchasing confidence in at the beginning of the second quarter, monthly panel shipments bluffs type fell by 19.3% in April, as the demand increase in North America and China 618 good performance to give confidence in the market of sales promotion in May and June shipment panel gradually restored, the second quarter panel shipped 65.8 million, year-on-year decline narrowed, fell by 8.5%, driven by upgrade size structure, area of 4020 square meters of shipment, Year-on-year growth was 1.1 per cent.
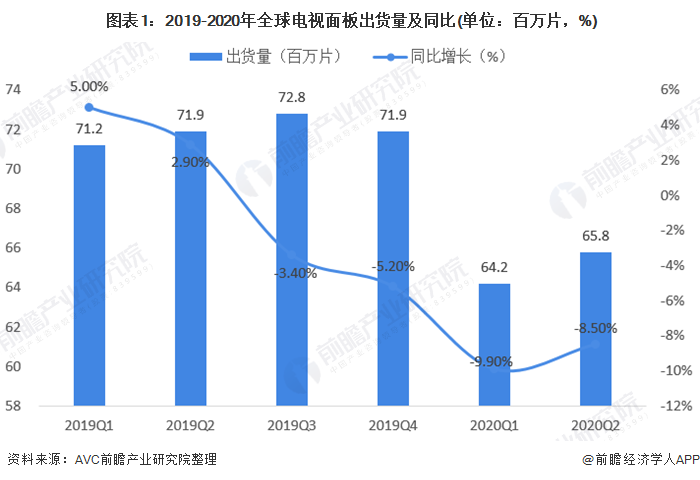
Figure 1: Global TV Panel Shipments and year-on-year (unit: million, %)
Reconstruction of production capacity pattern: The Korean plant is withdrawn, and the production capacity of Mainland China accounts for 50%.
South Korean panel manufacturers from the second half of 2019 to actively self-help, a large withdrawal of LCD TV panel capacity. On the other hand, Chinese panel manufacturers continue to release new production capacity, production capacity gathered in the Chinese mainland, the global LCD TV panel production capacity competition pattern has changed dramatically. In 2019, China's LCD TV panel manufacturers accounted for nearly 50% of the total production area. The production capacity continues to increase, and the global LCD TV panel production area is highly concentrated in Chinese mainland manufacturers.
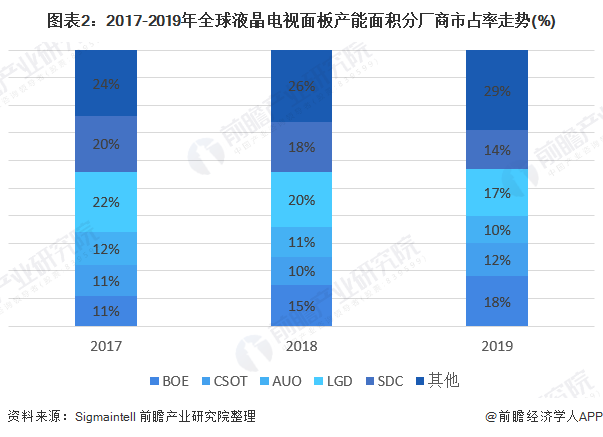
Chart 2: Trend of market Share of global LCD TV Panel production Surface integration manufacturers from 2017 to 2019 (%)
BOE maintained the top spot, CSOT played catch-up actively, and Korean factories slashed production influenced by the adjustment of product structure, BOE shipments declined significantly in the first half of 2020, but remained the top in the industry. CSOT actively pursued and narrowed the gap with BOE in market share. Meanwhile, shipments of HKC, CEC PANDA and CHOT continue to grow at a high rate. The area of TV panel shipments in mainland China exceeds 50% for the first time, and the power of the industry will be further enhanced.
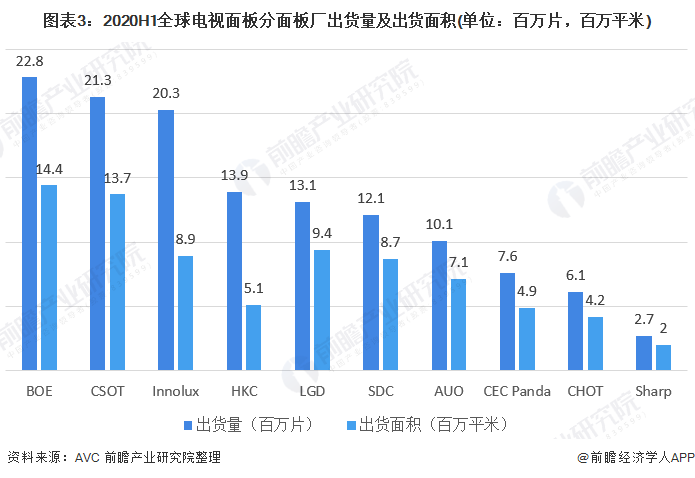
Figure 3:2020H1 Global TV Panel Sub-panel Factory shipments and Shipping area (unit: million pieces, million square meters)
Panel prices fluctuated sharply in the first half of 2020, and began to rise in June.
In early 2020, due to the outbreak of the epidemic, the supply of panels was relatively tight in the short term. In February, the price increase of panels increased. At the end of March, panel production basically resumed, while demand decreased, panel stopped rising. After entering the second quarter of 2020, the panel price declined again. Since June, affected by the increase of market demand in North America and Western Europe and the excellent promotion performance of China 618, the market confidence was high, the brand increased the purchase volume in the third quarter to compete for the market, and the panel price rebounded again. Is expected the third quarter of 2020 panel prices under the imbalance between supply and demand will continue to grow rapidly, but the TV brand at home and abroad continue to fight for market share at a lower price, cost pressures will soon face, at the same time in the fourth quarter of the global consumer market in the shadow of the autumn/winter outbreak may repeatedly is unclear, brand procurement strategy or to conservative, panel prices will limit on market expectations of inflation, or into a smooth channel.
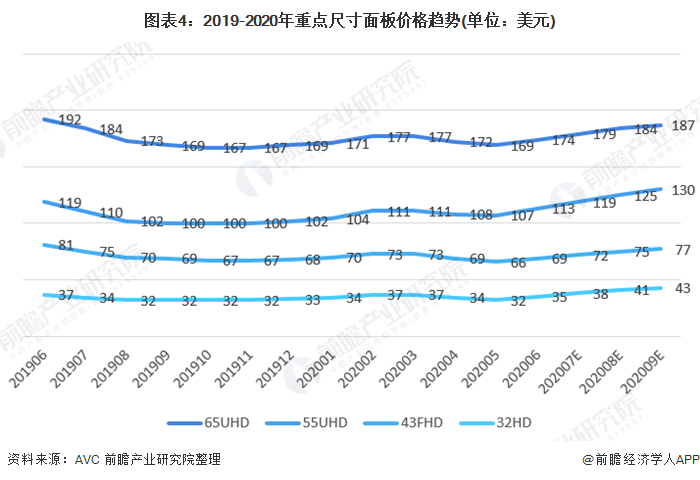
Chart 4:20 Key Dimensions Panel Price Trends in 2020 (IN USD)
8K industrial chain is becoming mature and is expected to usher in high speed growth in 2021
In terms of improving picture quality, one of the most important directions is to improve resolution. At present, 4K has been popularized and 8K has become a hot spot in the industry. The launch of 8K products is expected to accelerate the improvement of product structure and increase profitability. The panel factory actively plans 8K products. At present, the main manufacturers are Samsung Display (SDC) and AUO (AUO), but BOE, Huaxing Optoelectronics and others all have active plans. From the perspective of downstream brands, almost all the main brands will join the 8K camp by the beginning of 2020, among which Samsung Electronics is the most active.
With the breakthrough of 8K's technical bottleneck and the maturation of the industrial chain, the cost of 8K's panel will fall accordingly, driving the improvement of shipment scale and permeability. It is expected that the size of the global 8K panel market will double in 2020 compared with 2019, and the shipments of 8K LCD TV panels will reach 1.6 million units in 2021.In 2022, the global scale of 8K is expected to exceed 7 million, with the penetration rate increasing to 2.7%.
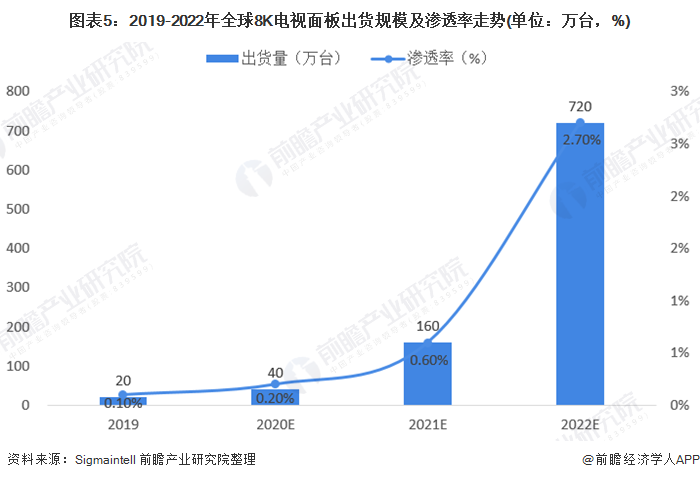
Chart 5: Trend of global 8K TV panel shipment scale and penetration rate from 2019 to 2022 (unit: 10,000 units, %)
The above data are from the Analysis Report on The Production and Sales Demand and Investment Forecast of China's Panel Industry issued by Foresight Industry Research Institute. Meanwhile, Foresight Industry Research Institute provides industrial big data, industrial planning, industrial declaration, industrial park planning, industrial investment attraction and other solutions.