


Forecast of large size LCD panel shipments by application category in 2021
2021.01.06
The bottom line: Omdia expects strong demand for laptop display panels to continue through at least the first half of 2021. Demand for the new semester and the expansion of remote work will be the main drivers. Panel makers are focusing more on the display panel business. Samsung displays will exit its LCD panel business in the first quarter of 2021. As a result, other panel makers are vying for the share vacated by Samsung's withdrawal. Shipments of LCD TV panels are likely to decline 5 percent year on year in 2021 (YoY). As the position in the LCD TV market has been fixed, China's first-line panel manufacturers pay more attention to the development of IT panel business.
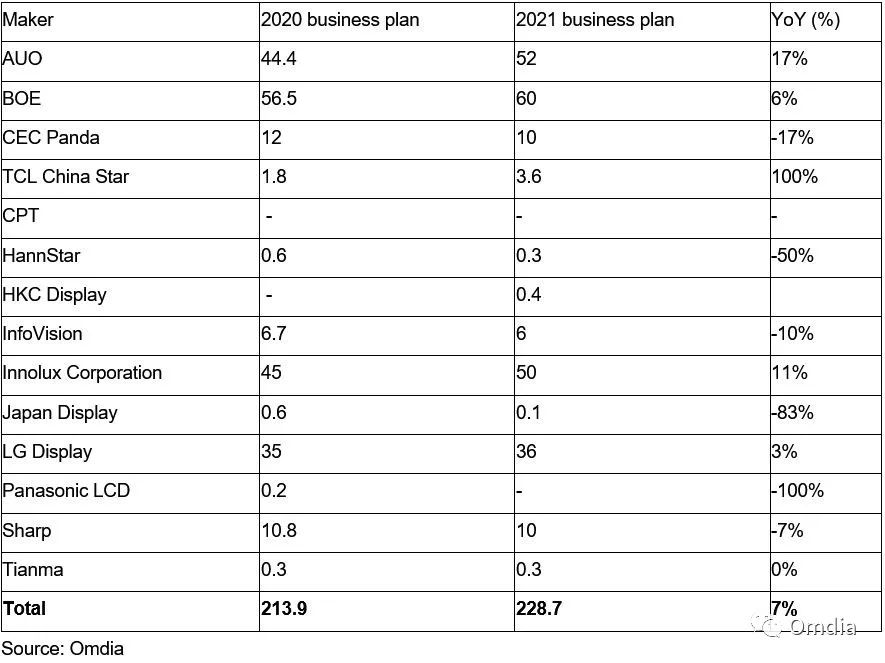
Panel makers believe demand for laptop panels will continue to be strong, and expect 7% annual growth in 2021
On the demand side, Omdia expects strong demand for notebook PC panels to continue through at least the first half of 2021. Demand from the new school year and the expansion of telecommuting will be the main drivers. This demand is mainly driving shipments of low-end and cheaper laptop panels, such as the TN HD class, in the 11.6-14 inch range.
On the supply side, panel makers are shifting their focus from TVS to IT displays, especially for laptops that use advanced technologies such as in-board switching (IPS) and high frame rates, boosting margins. There is a shortage of drive IC and power IC for laptop display panels, which could last until 2021. This will help in the short term with tight supply/demand and stronger prices for laptop display panels.
Taiwan's panel makers are actively increasing shipments of laptop display panels in their 2021 business plan. They are shifting production capacity allocated to TV panels and vertical alignment (VA) technology to make IPS and IT display panels in search of better profits. Mainland panel makers, particularly TCL Huaxing Optoelectronics, are also aggressively improving their product portfolios as they try to compete with BOE. HKC Display is also noteworthy, as IT is expanding its footprint beyond TVS to IT Display panels and starting a new laptop panel business in the fourth quarter of 2020. Lg Display, a traditionally strong IT display maker, is also aggressively pushing the laptop panel business. Lg Display plans to exit the traditional LCD TV panel business, but IT is maintaining its LCD IT panel business, including laptop panels. Lg Display's IT display panel business is the biggest driver of revenue and profit, so IT will be more aggressive.
Table 1: Laptop display Panel shipment Estimate of various manufacturers in 2021 (unit: million)
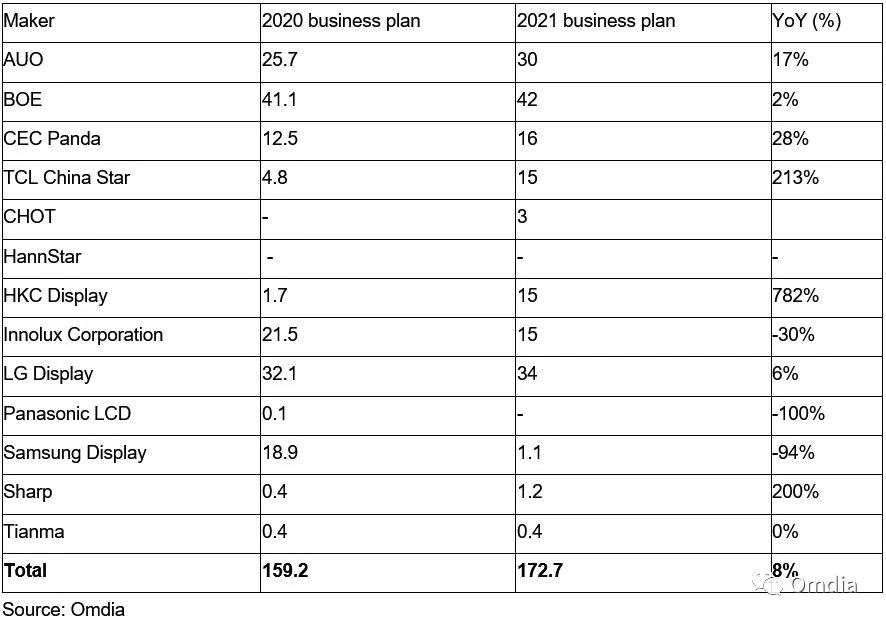
After Samsung exited the LCD panel business, panel makers are aiming to increase their share of the display panel market by 8% year on year
On the demand side, in the case of the COVID-19 pandemic, the demand for laptops and monitors from the start of the new school year and the expansion of telecommuting will be the biggest driver. Normally, commercial demand leads display shipments, but COVID-19 has led to a surge in consumer shipments, such as for game displays. This is because, having to stay at home and maintain a social distance, people need to be entertained at home. These trends will continue through at least the first half of 2021. When the New Year comes, the business market also increases to replace old equipment and buy new equipment for new employees.
On the supply side, panel makers are eager to boost their display panel business for two reasons: First, Samsung displays will exit the LCD panel business in the first quarter of 2021. As a result, panel makers will compete for the share unleashed by Samsung displays. Second, since most of the production is on the same production line, it is easier to shift the allocation of capacity from TVS to display panels. These will be helpful in managing the price of TV panels and display panels in 2021.
TCL Huaxing optoelectronics and Huike are the most aggressive in the display panel business. TCL Huaxing Optoelectronics has acquired Samsung's suzhou production line and module factory and plans to use some of its capacity for display panel production, while Huike is trying to diversify its panel business portfolio. However, panel makers appear to be aiming higher for display panel shipments in 2021 than demand forecasts. LCD TV panel prices have been rising since the third quarter of 2020, so panel makers may change their product mix and allocate more capacity to produce LCD TV panels in 2021. This could lead to lower actual output and shipments of display panels in 2021.
Samsung's display panel shipments accounted for 12 percent of its total shipments in 2020. As it exits the LCD business, the panel maker has an aggressive LCD panel business plan for 2021 in order to capture Samsung's display share. This is a great opportunity for panel vendors who want to expand their business portfolio, especially in the VA monitor camp. However, curved displays are expected to see their share of game displays decline after Samsung's display exits the market. That's because Samsung Displays has more than 70 percent of the curved display market, and other panel makers aren't ready to take over such a large share.
Table 2 forecast of LCD Panel Shipments by manufacturers in 2021 (unit: million)
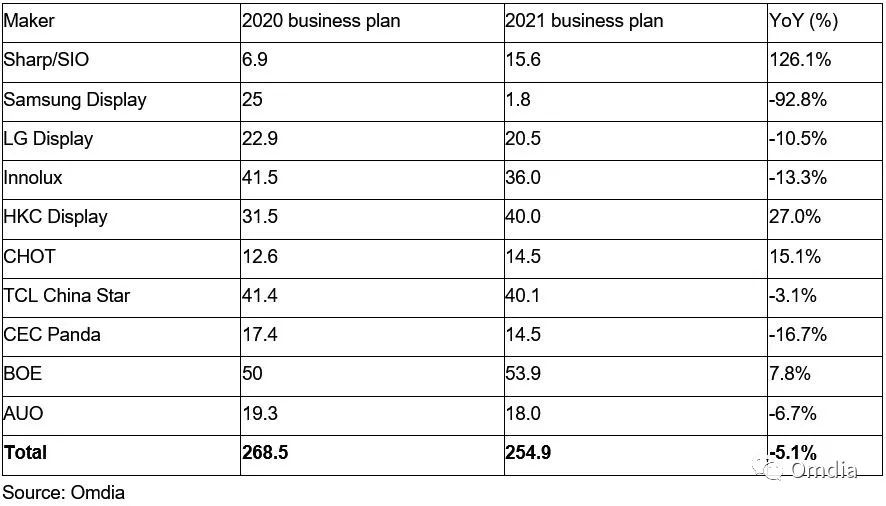
Shipments of LCD TV panels are expected to drop 5% year-on-year in 2021 due to strong DEMAND for IT panels and a shortage of components
Unlike IT display panels, Omdia expects LCD TV panel shipments to decline 5 per cent year on year in 2021. South Korean and Taiwanese panel makers are giving up on competition with China's 10.5 - generation line. South Korean panel makers are exiting the LCD TV panel market, while Taiwanese panel makers are trying to shift more LCD TV panel production to IT display panels.
In addition to newcomers such as SIO (Sharp and Guangzhou Foxconn) and Huike, the Chinese panel makers that have won the LCD TV war are also reducing their focus on LCD TV panel shipments. As its position in the LCD TV market has stabilized, front-line panel manufacturers in Mainland China are now paying more attention to IT display panel business. This is also a good strategy for managing the price of LCD TV panels. In addition, there are shortages of key components such as display drive IC, glass and polarizer. These shortages could last until 2021. So far, the component shortages have affected China's second - and third-tier panel makers. However, the latest industry observations indicate that the component shortage will affect front-line panel manufacturers even from the end of 2020. The situation will worsen in the first quarter of 2021. It seems unlikely that the shortage, especially of display panel driven IC, will be alleviated within 2-3 quarters. A shortage of components is one factor limiting shipments of LCD TV panels in 2021.
Demand worries are growing. TV demand will be strong in the second half of 2020, but only in a few developed regions. It is unrealistic to expect a rapid recovery elsewhere. The surge in TV panel prices will soon affect demand in the end market.
Global LCD TV shipments in 2020 were smaller than the previous four years. In the current environment, TV brand leaders are particularly eager to gain more market share, so other brands are forced to follow suit. Strong DEMAND for IT displays will help stabilize LCD TV panel prices in early 2021.
Table 3 estimated SHIPMENTS of LCD TV Panels from various manufacturers in 2021 (unit: million)
Source: Omdia